iTrustCapital vs Unchained IRA (2026): US Fees, Spreads, 50-State Legality & NMLS Compared
- iTrustCapital $1k Pro / Simple
- $24.00 Pro · $24.00 Retail
- Unchained IRA $1k Pro / Simple
- $14.00 Pro · $24.00 Retail
- US State Availability
- iTrustCapital: 51/51 · Unchained IRA: 50/51
- NYDFS BitLicense (NY)
- iTrustCapital: Yes · Unchained IRA: No
- NMLS Registry IDs
- #N/A vs #1900773
- 2026 Tax Reporting
- IRS Form 1099-DA + Form 8949 Compatible
▣ VERIFIED 1200×675 QUANT DOSSIER SNAPSHOT CARD[EXPAND TERMINAL PREVIEW ▾]
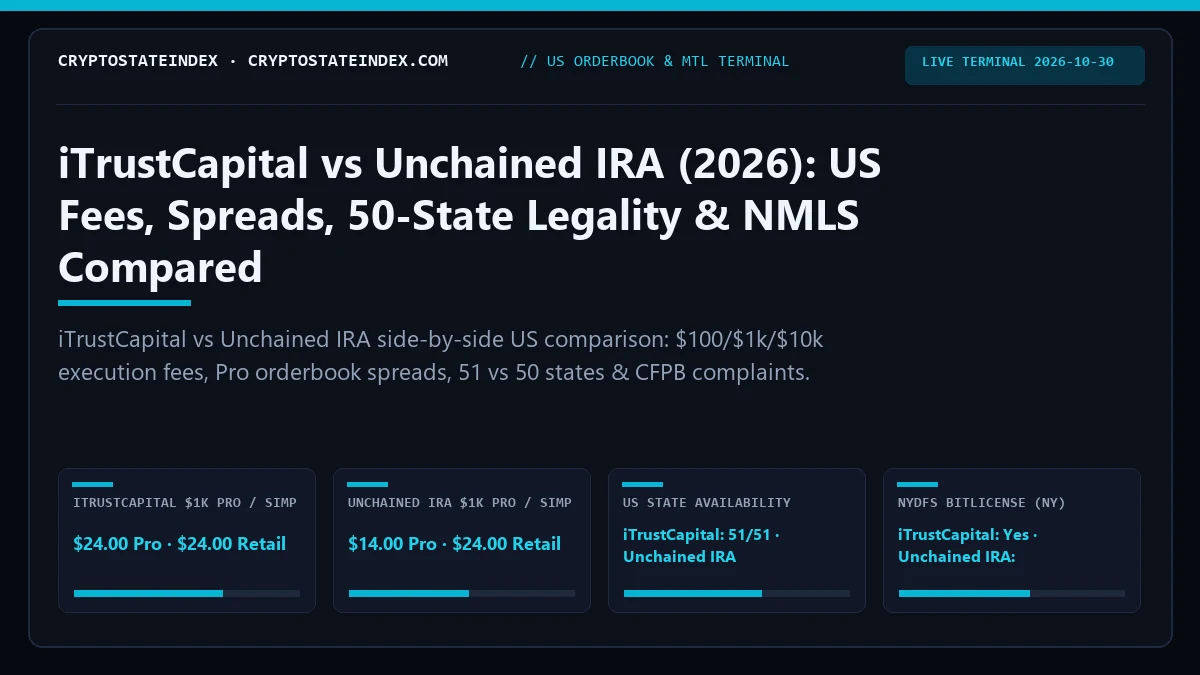
1. Visual Trade Cost Comparison ($100, $1,000 Retail, $1,000 Pro & $10,000)
2. Complete US Fee, Regulatory & Product Matrix: iTrustCapital vs Unchained IRA
| Benchmark Dimension | iTrustCapital | Unchained IRA |
|---|---|---|
| US Legal Entity | iTrustCapital, Inc. (Custodian: Fortis Bank / Fortress Trust; Liquidity: Coinbase Prime / Fidelity) | Unchained Capital, Inc. (IRA Administrator: Fortis Bank) |
| NMLS ID & State MTLs | NMLS #— (51 MTLs) | NMLS #1900773 (48 MTLs) |
| New York (NYDFS) Status | Available to NY residents via regulated trust custodian structure. | Available in 49 US states + DC. |
| Available US Jurisdictions | 51 / 51 | 50 / 51 |
| Retail Instant Buy Fee + Spread | 1.00% + 20 bps | 1.00% + 20 bps |
| Pro Orderbook Maker / Taker | No Separate Pro Book | 0.50% / 1.00% |
| $100 Round-Trip Cost (Retail) | $2.40 | $2.40 |
| $1,000 Round-Trip Cost (Retail) | $24.00 | $24.00 |
| $1,000 Round-Trip Cost (Pro Tier) | $24.00 | $14.00 |
| $10,000 Round-Trip Cost | $240.00 | $190.00 |
| $100/mo Annual DCA Cost | $28.80/yr | $28.80/yr |
| ACH Deposit / Withdrawal | $0.00 / $0.00 | $0.00 (IRA Rollover/Transfer) / $0.00 |
| Fedwire Deposit / Withdrawal | $0.00 / $0.00 | $0.00 / $0.00 |
| Supported Crypto Assets | 40 | 1 |
| Lightning Network Support | No | No |
| CFPB Consumer Complaints | 0 / Partner Routed | 0 / Partner Routed |
| IRS Tax Forms | 5498, 1099-R | 5498, 1099-R |
3. 50-State + DC Licensing Delta
States where iTrustCapital is legal but Unchained IRA is restricted: New York (NY)
States where Unchained IRA is legal but iTrustCapital is restricted: None (Available in same states)
Overall State Reach Winner: iTrustCapital (51/51 vs 50/51).
4. Scenario Winner Breakdown
- Lowest $1,000 Active Trading Cost: Unchained IRA ($14.00 round-trip).
- Lowest $100/mo Automated DCA Cost: iTrustCapital ($28.80/year).
- New York Resident Eligibility: iTrustCapital.
- Full Dossiers: iTrustCapital Dossier · Unchained IRA Dossier
Who Should Choose iTrustCapital vs. Who Should Choose Unchained IRA (2026 Decision Matrix)
2026 US Execution & Compliance Matrix| US Trader / Investor Profile | Who Should Choose (Optimal Use Case) | Who Should Avoid (Cost or Regulatory Friction) | Recommended Execution Protocol |
|---|---|---|---|
| Cost-Minimizing Orderbook Traders ($1k–$50k) | Choose Choose Unchained IRA for lower $1,000 round-trip execution cost ($14.00 vs $24.00). | Avoid Avoid executing market buys on either platform's Retail Simple interface ($24.00 vs $24.00). | Always place limit Maker orders on the Pro Orderbook tier after funding via $0.00 ACH. |
| New York & Strict MTL State Residents | Choose Choose iTrustCapital if you reside in New York (51/51 vs 50/51 states). | Avoid Avoid attempting VPN workarounds if your state is excluded under NMLS Money Transmitter rules. | Check our 51-Jurisdiction State Matrix to verify exact state eligibility before completing KYC. |
| Automated Monthly DCA Investors ($100/mo) | Choose Choose iTrustCapital ($28.80/yr vs $28.80/yr on $100/mo DCA). | Avoid Avoid funding recurring buys with a debit card (adds 2.99%–3.99% processing fees). | Link a US checking account via Plaid ACH ($0 deposit fee) and schedule limit or zero-fee recurring buys. |
Orderbook Fee & Spread Microstructure (iTrustCapital vs Unchained IRA): When evaluating iTrustCapital (iTrustCapital, Inc. (Custodian: Fortis Bank / Fortress Trust; Liquidity: Coinbase Prime / Fidelity)) against Unchained IRA (Unchained Capital, Inc. (IRA Administrator: Fortis Bank)), the primary cost driver for US traders is the spread between retail instant-buy widgets and institutional limit orderbooks. On a $1,000 round-trip transaction, iTrustCapital charges $24.00 on its retail interface and $24.00 on its $0.00 monthly account fee + flat 1.00% per crypto trade (precious metals: $50 over spot/oz gold), whereas Unchained IRA charges $24.00 retail and $14.00 on its $250 annual IRA vault maintenance fee ($0 initial setup on qualifying rollovers) + 0.25%–1.00% trading fee.
50-State + DC Licensing & Regulatory Footprint: iTrustCapital holds 51 state Money Transmitter Licenses (NMLS #Exempt) covering 51/51 US jurisdictions, while Unchained IRA holds 48 state MTLs (NMLS #1900773) covering 50/51 jurisdictions. New York availability is supported on iTrustCapital and restricted on Unchained IRA.
Banking Rails, ACH Clearing Holds & Self-Custody: Both platforms support US banking rails, with iTrustCapital charging $0.00 for ACH deposits ($0.00 Fedwire) and Unchained IRA charging $0.00 (IRA Rollover/Transfer) for ACH deposits ($0.00 Fedwire). Standard ACH deposits incur a 3–7 business day clearing hold before on-chain withdrawal to a hardware wallet.
2026 IRS Form 1099-DA & Portfolio Tax Reconciliation: iTrustCapital issues 5498, 1099-R (Tax-Advantaged IRA (0% capital gains tax on trades inside Traditional/Roth/SEP IRA; no Form 8949 required)) and Unchained IRA issues 5498, 1099-R (Tax-Advantaged IRA (Fortis Bank / Unchained files IRS Form 5498 & Form 1099-R)). Investors using both venues simultaneously must track cost basis separately per account under IRS Revenue Procedure 2024-28.
Frequently Asked Questions (US Regulatory & Execution Reference)
VERIFIED Q&A PROTOCOLIs iTrustCapital cheaper than Unchained IRA for US crypto traders?
On a $1,000 round-trip trade using the lowest-fee tier, iTrustCapital costs $24.00 compared to $14.00 on Unchained IRA. On standard retail instant buy, iTrustCapital costs $24.00 vs $24.00 on Unchained IRA.
Which states allow iTrustCapital vs Unchained IRA?
iTrustCapital is available in 51/51 US jurisdictions, whereas Unchained IRA is available in 50/51 jurisdictions.
How does iTrustCapital vs Unchained IRA impact 2026 IRS Form 1099-DA and Rev. Proc. 2024-28 tax reporting?
For the 2026 tax year, regulated US digital asset brokers report gross proceeds and covered cost basis on IRS Form 1099-DA under IRC Section 6045. Taxpayers interacting with iTrustCapital vs Unchained IRA must maintain wallet-by-wallet (or account-by-account) cost-basis lot allocation under IRS Revenue Procedure 2024-28 and reconcile dispositions on Form 8949 and Schedule D.
What is the difference between Retail Instant Buy and Pro Orderbook execution for iTrustCapital vs Unchained IRA?
Across audited US platforms relevant to iTrustCapital vs Unchained IRA, standard retail 'Simple' or 'Instant Buy' widgets embed a 100 to 200 bps principal spread on top of a 0.99%–1.49% convenience fee (~$18–$29 per $1,000). Routing the exact same USD deposit through a Central Limit Order Book (CLOB) such as Kraken Pro, Coinbase Advanced, Gemini ActiveTrader, or Bitstamp US reduces total execution cost to 20–60 bps ($2.00–$6.00 per $1,000).
How do NMLS Money Transmitter Licenses and the NYDFS BitLicense apply to iTrustCapital vs Unchained IRA?
In the United States, custodial crypto platforms must register federally as a FinCEN Money Services Business (MSB) under 31 CFR 1022.380 and hold state-by-state Money Transmitter Licenses tracked in NMLS Consumer Access. Serving New York residents additionally requires a NYDFS BitLicense (23 NYCRR Part 200) or a New York Limited Purpose Trust Company charter.
FinCEN / NMLS / Form 1099-DA Execution Checklist
Toggle each statutory & orderbook execution check before routing USD via ACH or Fedwire:
State MTL, BitLicense & Fee Schedule Alert Wire
Receive deterministic alerts when a US exchange changes Maker/Taker fees, NMLS state coverage, or 1099-DA reporting: